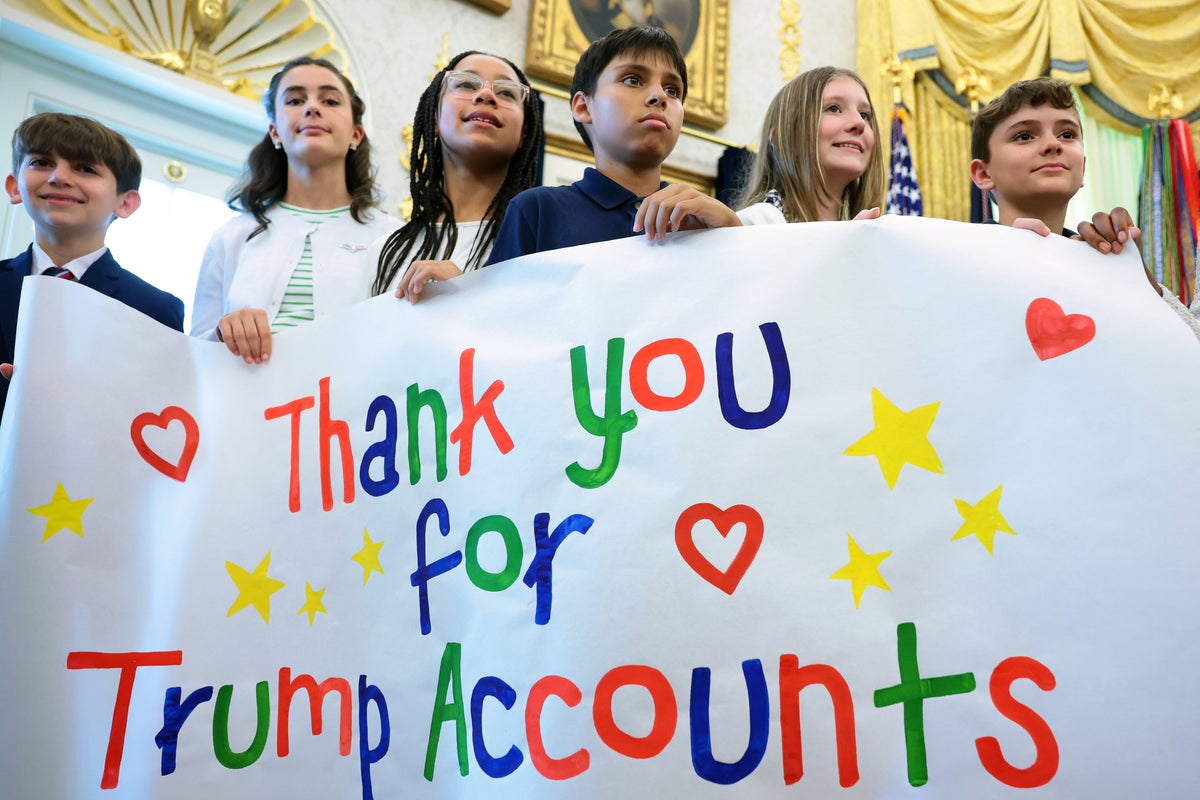
The U.S. and Canada both provide children with money intended to build savings, but they handle the money differently—especially once beneficiaries reach adulthood. The key divergence is what happens to the accounts and any education-related funds when young people transition out of eligibility.
Across the coverage, a shared focus is the design of the rules around keeping the savings. One account framework emphasizes how funds remain accessible later in life, while the other places greater weight on conditions for retaining education-linked support. The Conversation notes that automatic accounts can help narrow savings gaps, but also flags a risk in Canada’s approach: low-income young adults who may need education support most could be more likely to see funds taken back under certain rules. Meanwhile, The Independent frames the contrast primarily through the differing adulthood outcomes for recipients.