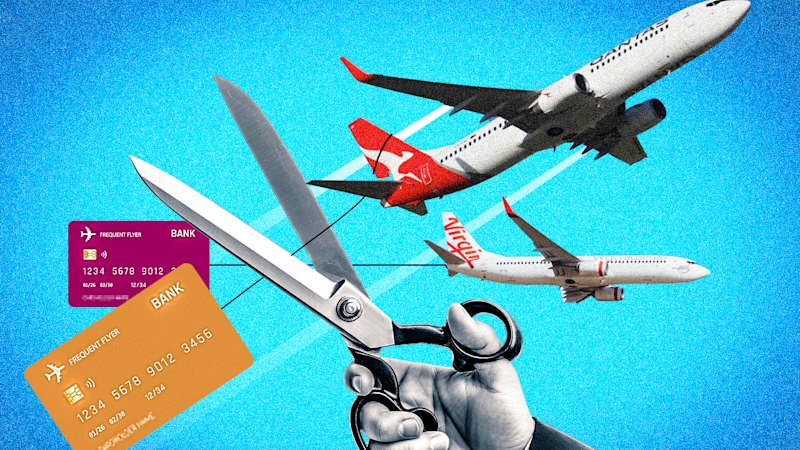
Australia’s Reserve Bank is introducing restrictions on credit card surcharges that will take effect soon, affecting how consumers can earn frequent flyer points via card payments. The changes alter the conditions under which merchants may pass on surcharge costs and the pricing models that some credit cards rely on for rewards.
Across outlets, the focus is on what the policy shift means for points earned without flying—particularly purchases made using credit cards linked to airline loyalty programs. The reporting highlights that the rewards landscape is likely to change because payment costs and merchant acceptance of specific fees can influence which card products remain attractive and how rewards are structured.
While the articles align on the central policy trigger and the likelihood of impact on card-linked points earning, they differ mainly in emphasis and audience framing—some concentrating on consumer takeaways and practical implications, others on the regulatory basis and how surcharge rules cascade through credit card economics and loyalty schemes.