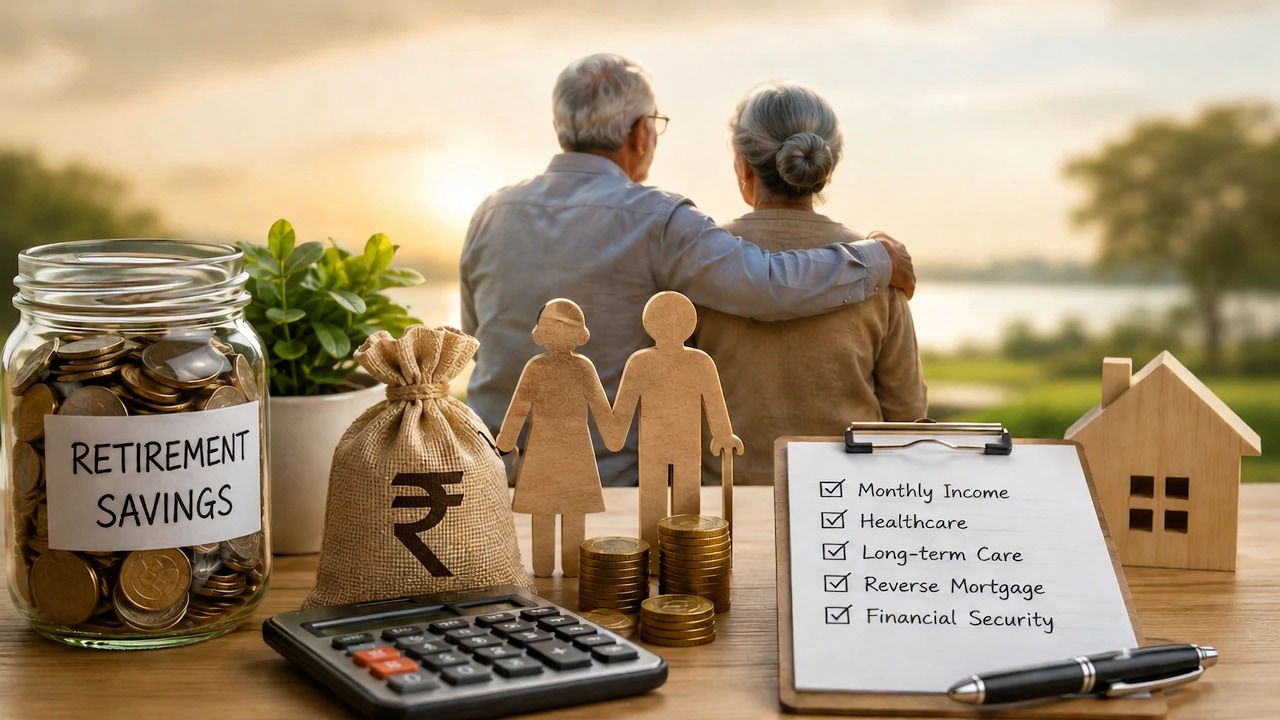
Retirement planning guidance focuses on the idea that retiring at 60 is not the main problem for people; the bigger risk is running out of money later in life, particularly around age 75. The discussion emphasizes that financial readiness depends on how long people may need income and how unexpected expenses are covered.
Outlets describing the same theme stress that health-related costs are central to planning. Securing health insurance before retirement is presented as an important step, since medical expenses can rise and can disrupt budgets. Sources also commonly point to the need for separate reserves—such as a medical fund and an emergency fund—to provide flexibility when health events or other urgent situations arise.
While the articles share the same core message, they differ slightly in emphasis, with some focusing more on the timing of health coverage and others on the structure of savings to extend financial security into later years. Together, they frame retirement at 60 as potentially workable if planning accounts for a longer retirement horizon and higher likelihood of health spending.