FICO Crashes Most Since 2004 As Pulte's Mortgage Score Shakeup Threatens Its Moat
FICO Crashes Most Since 2004 As Pulte's Mortgage Score Shakeup Threatens Its Moat
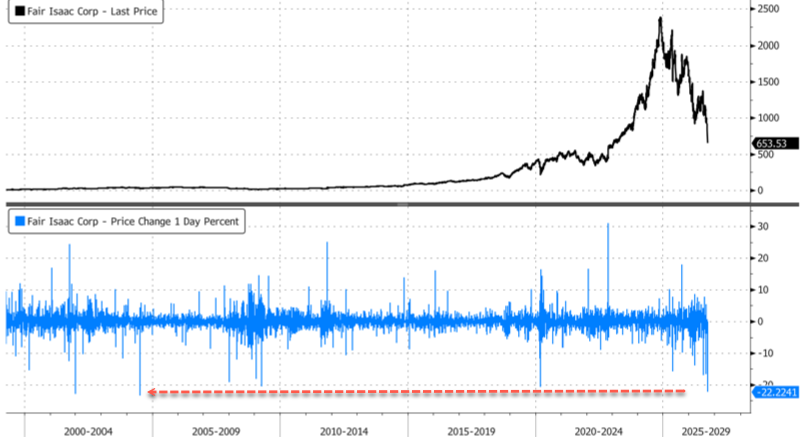
Fair Isaac, the company that produces FICO scores, saw its shares crash the most in 22 years early Tuesday in cash trading after Federal Housing Finance Agency Director Bill Pulte announced on X that a mortgage-pricing change that Wall Street analysts say could accelerate adoption of rival VantageScore and undermine FICO's moat.
"We are Simplifying Mortgage Pricing following feedback from lenders and consumers. Instead of two separate pricing grids, which makes zero sense, Fannie and Freddie are hereby moving to ONE PRICING GRID with VantageScore joining the existing FICO Classic pricing grid," Pulte posted on X Monday.
We are Simplifying Mortgage Pricing following feedback from lenders and consumers. Instead of two separate pricing grids, which makes zero sense, Fannie and Freddie are hereby moving to ONE PRICING GRID with VantageScore joining the existing FICO Classic pricing grid. pic.twitter.com/g9h1EqsDca
— Pulte (@pulte) September 28, 2026
Pulte cited a press release from Rocket Mortgage that stated: "Rocket Mortgage did an extensive study that helped the company determine VantageScore 4.0 opens access to some clients who wouldn't be served otherwise, and many are able to secure a mortgage on better pricing terms. For those who saved money with VantageScore 4.0, the savings was an average of $1,600 at closing. FHFA and Director Pulte are encouraging competition and innovation in pilot programs."
The below is from Rocket Mortgage. Only happens because because of President TRUMP:
“Rocket Mortgage did an extensive study that helped the company determine VantageScore 4.0 opens access to some clients who wouldn't be served otherwise, and many are able to secure a mortgage on…
— Pulte (@pulte) September 28, 2026
The change gives lenders a stronger incentive to adopt VantageScore, potentially lowering costs for homebuyers while threatening FICO's market share and pricing power. Traders responded by sending FICO shares tumbling 22% earlier this morning - the largest intraday decline since July 13, 2004.
Here's what Wall Street analysts had to say (courtsey of Bloomberg):
FT Partners
With pricing now in line, VantageScore could see increased adoption, with a lower hurdle for more favorable LLPA pricing, says analyst Craig Maurer
The move will allow more borrowers to qualify for lower rates, adding to VantageScore's existing cost advantage
Under a common LLPA grid, borrowers whose VantageScore 4.0 exceeds their classic FICO scores could qualify for a more favorable pricing bucket when selected
TD Cowen
The news presents a risk to FICO because it's not about which model is more predictive of defaults; it's about the regulators shifting LLPA pricing to get lenders to use VantageScore over FICO, says housing policy analyst Jaret Seiberg
One long-term worry is that it creates an incentive for FICO and VantageScore to compete on producing scores that result in lowest LLPAs rather than on the risk of default
RBC (rates FICO as outperform)
The news meaningfully raises the risk of score shopping, where lenders select whichever model produces the more favorable credit score and a lower mortgage interest rate, says analyst Ashish Sabadra
With unified pricing, VantageScore's market share gains could accelerate
Another risk is FICO may need to hasten its shift away from traditional per-pull origination fees toward other pricing structures to defend its economics
Deutsche Bank analyst Faiza Alwy asked clients, "Where is the moat?"
Alwy provided clients with her first take on the developments:
Single pricing grid plus Rocket to use VS4 as preferred credit scoring model
There were two important and negative developments that happened post-close yesterday. The first one was FHFA Director Pulte indicating on X that based on lender feedback, the GSEs will operate on one LLPA grid and VantageScore 4.0 (VS4) will now join the existing FICO Classic grid. This means that the VS4 20 point discount to FICO has been removed by the FHFA and both scores will now be treated the same by the GSEs. This would likely in and of itself result in higher number of mortgages that will see favorable pricing with VS4 vs. FICO Classic. We would have expected continuing gaming and for lenders to optimize pricing with this change. However, the announcement from Rocket this evening following this change is meaningfully negative and consequential for FICO.
Rocket Mortgage announced that it will become the first mortgage lender to use VS4 as its preferred credit scoring model for all eligible loans. Specifically, during 4Q26, the company will default to VS4 for mortgages that will be delivered to GSEs, VA home loans and any other eligible mortgages. The company noted that after four months of testing, it found that VS4 helped more clients qualify and move forward in the mortgage process, while also reducing credit scoring costs. Rocket is a top mortgage originator with ~5-6% share (possibly higher following the acquisition of Mr Cooper in 4Q25).
We're not entirely sure what the words "preferred" and "default" exactly mean at the moment but the worst case interpretation for FICO would be that Rocket Mortgage will not be pulling FICO scores at all when eligible. Important to note that the above excludes mortgages for investment properties and second homes, HELOCs, FHA loans, jumbo loans and some other products. Rocket Pro, the division that provides home loans through mortgage broker partners, will continue to provide both VantageScore and FICO to mortgage brokers. Rocket Pro comprised about 30% of the company's origination volume in 2025. We estimate that in aggregate about both scores would be pulled 50% of the time (at origination). Encouragingly for FICO, Rocket did indicate that they will continue to evaluate new options as they become available (a likely reference to FICO 10T).
Could other lenders follow suit? It would make sense to assume that UWM would follow suit but we note that UWM operates exclusively as a wholesale lender and competes directly with RocketPro. Other lenders were not particularly active in the pilot program, so we expected limited movement near-term.
What does this mean for FICO's mortgage strategy? FICO's management continues to believe that notwithstanding significant price increases in the last few years, the score remains under-priced relative to the value it is providing. We expect FICO's 2027 approach to pricing to be variable by lender with the company offering and implementing the performance model for some lenders. Ultimately this makes us much less confident with respect to FICO's mortgage revenue algorithm at least in the near-term. That said, we believe the non-GSE securitization market will require FICO Classic for an extended period of time; recall that the FHFA has indicated it will provide both VS4 and FICO on all GSE loans that are securitized to investors. We suspect FICO will attempt to monetize the securitization channel or GSEs.
We will revisit our model as we gather additional information and the mechanics of these new late developments. In the interim, we expect FICO stock to understandably react negatively.
With FICO's competitive moat under pressure, this new development raises the risk of "score shopping," as lenders select the credit-scoring model that secures the most favorable mortgage pricing for prospective homebuyers.
Tyler Durden
Tue, 09/29/2026 - 10:55
3 hours ago