2 hours ago
Aramco CEO Eyes "Fourth & Fifth" Oil Export Routes To Break Hormuz Chokehold
ZeroHedge
23 hours ago
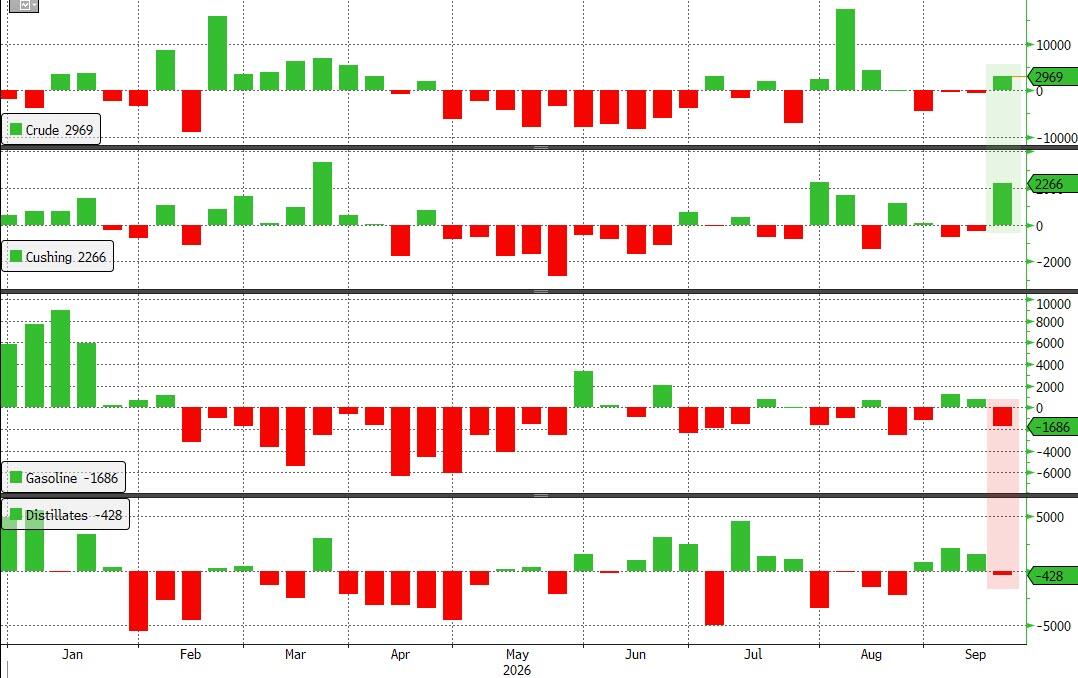
Oil Holds Highs After Total Crude Stocks Rose, US Production & Gasoline Dema...
ZeroHedge
1 day ago
"Developments Can't Be Ignored" As Brent Tumbles On Iran Talks, Saudi Pipeline R...
ZeroHedge
2 days ago
Saudis Signal Red Sea Oil Loadings Could Soon Resume For Asian Buyers
ZeroHedge
2 days ago
Iran's Fars Calls Reuters' Hormuz Reopening Story "Invalid" Ahead Of Trump's UN...
ZeroHedge
2 days ago
Oil Settles Near $100 as Hormuz Flows Stunt Rally
Bloomberg - Markets
2 days ago
Gulf states need 'good relations' with Iran as part of new security framework, Q...
Middle East Eye
4 days ago
CENTCOM Claims US Military Has Escorted A Billion Barrels Of Crude Out Of Hormuz
ZeroHedge
6 days ago
Winter Is Coming: Saudis Warn European Refiners Of Crude Shipment Disruptions Ne...
ZeroHedge
1 week ago
WTI Holds Losses As Crude Production Hits Record High, SPR/Cushing Near 'Tank Bo...
ZeroHedge
1 week ago
Iran does not need to beat the Americans militarily. It just needs to outlast th...
Middle East Eye
1 week ago
Oil Surges As Saudi Pipeline Crisis Puts 4% Of Global Supply At Risk; Bernstein...
ZeroHedge
1 week ago
Deepening oil market turmoil
Dawn (Pakistan)
1 week ago
UAE Meets With Iran Leaders As Tehran Teases Oman Shipping Deal
ZeroHedge
1 week ago
Piper Sandler Sounds Alarm: Shrinking Oil Buffers To Collide With Winter Demand
ZeroHedge
1 week ago
Twin Chokepoint Shock: Houthis Seize Mayyun Island In Bab el-Mandeb Strait As Ho...
ZeroHedge
1 week ago
Brent Nears $110 Then Tumbles On IEA Demand Destruction Warning As Houthis Threa...
ZeroHedge
1 week ago
Mideast Chaos Sends Supertanker Rates Soaring To $800,000 A Day
ZeroHedge
1 week ago
Hormuz a bit freer, but Iran war far from over
The Economic Times (India)
1 week ago
Oil Tanker Rates Hit Record Highs as Middle East Shipping Risks Soar
ZeroHedge
2 weeks ago
Brent Tops $102 As Mideast Conflict Intensifies, HSBC Hikes Oil Forecast
ZeroHedge
2 weeks ago
Brent Tops $100 As Gulf Conflict Escalates; UBS Warns US-Iran "Off-Ramp Remains...
ZeroHedge
2 weeks ago
"It's Pretty Tight": Vitol Chief Warns Of Global Fuel Squeeze As Refineries Max...
ZeroHedge
2 weeks ago
Chinese Oil Demand Unexpectedly Soars, Sending Shanghai Crude Above $100, With B...
ZeroHedge
2 weeks ago
"Three For Two": CENTCOM Destroys Iranian Tankers Near Kharg Island After IRGC T...
ZeroHedge
2 weeks ago
Hormuz Disruptions Could Drag Into Next Year, Japanese Tanker Giant Warns
ZeroHedge
3 weeks ago
Oil Tops $91, US Diesel Crack Near $100 As US-Iran Strikes Resume, Tehran Claims...
ZeroHedge
3 weeks ago
Iranian Gasoline Shortages Grow As US Blockade Bites
ZeroHedge
3 weeks ago
The Iran War Has Turned VLCCs Into $650,000-A-Day Assets
ZeroHedge
3 weeks ago
"Dark" Tanker Fleet Shatters Iran's Hormuz Stranglehold As Gulf Oil Exports Top...
ZeroHedge
4 weeks ago
Kuwait, Qatar Ramp Up Hormuz Oil Flows As Oman-Iran Talks Ease Supply Fears
ZeroHedge
4 weeks ago
WTI Rises After Big Product Draws, Tiny Crude Build, SPR Nears 'Tank Bottoms'
ZeroHedge
4 weeks ago
TotalEnergies CEO Reveals Cost To Move A Supertanker Through Hormuz
ZeroHedge
1 month ago
How China eased pressure on oil markets by halting purchases and relying on rese...
Middle East Eye
1 month ago
US vows to 'collapse' Iran with new sanctions as energy prices spike
Middle East Eye
1 month ago
Oil supertankers in Gulf are renting for $500,000 per day: Report
Middle East Eye
1 month ago
Saudis Offer To Sell Oil Near Oman, A Sign They're Sailing Dark Through Hormuz
ZeroHedge
1 month ago
"US Can't Bomb Its Way To Victory": Scotiabank Maps Bessent's Coming Economic Ha...
ZeroHedge
1 month ago
Hormuz Shock "Manifesting Itself In Cracks, Not Crude," Jefferies Says
ZeroHedge
1 month ago
US Now Expects Iran War Oil Supply Disruptions To Last Through End Of 2027
ZeroHedge
1 month ago
WTI Dips After Massive Crude Inventory Build, Big SPR Drain, Surge In Imports
ZeroHedge
1 month ago
Why the Middle East war still convulses the oil market
Jamaica Observer
1 month ago
Hormuz Traffic Sank To Just Six Vessels Monday
ZeroHedge
1 month ago
Why the Middle East war still convulses the oil market
Dawn (Pakistan)
1 month ago
US SPR Falls Below 300 Million Operational Limit As Oil Drain Unexpectedly Surge...
ZeroHedge
1 month ago
Race To Reopen Hormuz Intensifies As Global Supply Chain Stress Remains At COVID...
ZeroHedge
1 month ago
Give Them An Inch...
ZeroHedge
1 month ago
WTI Maintains Losses After Another SPR Drain, Distillate Stocks At 30-Year Seaso...
ZeroHedge
1 month ago
Brent Bounces As Houthis Attack, Sink Vessel Off Yemen With Sea Drone
ZeroHedge
1 month ago
Saudi Aramco reports bumper profits as it bypasses Strait of Hormuz
Middle East Eye
1 month ago
Groundhog Day
ZeroHedge
1 month ago
Widening cost of conflict
Dawn (Pakistan)
1 month ago
Crude Inventories Have Fallen To "Precariously Low" Levels
ZeroHedge
1 month ago
Hormuz Ship Traffic Edges Higher, But Kpler Warns Gulf Crude Exports Remain Impa...
ZeroHedge
1 month ago
WTI Holds Spike After Big Crude Draw, SPR Drain Continues As Cushing Stocks Stuc...
ZeroHedge
1 month ago
Gulf Bond Boom: Record Borrowing Fuels Race To Future-Proof Against Hormuz Shutd...
ZeroHedge
1 month ago
Massive Relax
ZeroHedge
1 month ago
Iran, Oman Hold Hormuz Talks As US Pauses Airstrikes For Second Day
ZeroHedge
1 month ago
US Pauses Iran Bombing Campaign As Saudi-Houthi Red Sea Front Erupts
ZeroHedge
1 month ago
Oil Tanker Makes Red Sea U-Turn After Houthi Threats, Reroutes Around Africa In...
ZeroHedge
2 months ago
"It's Getting Worse": HSBC Warns Commodities Face Squeeze As Chokepoint Chaos Sp...
ZeroHedge
2 months ago
Seven Pipeline Projects That Could Break Iran's Grip On Hormuz Chokepoint
ZeroHedge
2 months ago
RBC Commodities Chief Warns "War Entering Dangerous Phase" As Chokepoint Chaos R...
ZeroHedge
2 months ago
Oil Soars To Six-Week Highs Amid Trump Threats, US Production Dip, & 'Tank B...
ZeroHedge
2 months ago
Iran Warns US Of 'Infrastructure For Infrastructure' War, Will Control Hormuz As...
ZeroHedge
2 months ago
Japan Trade Chief Says Hormuz Off-Limits As Hostilities Reignite
ZeroHedge
2 months ago
UN Maritime Boss Warns Ships To Avoid Hormuz As Transits Continue
ZeroHedge
2 months ago
WTI Dips As US Crude Production Hits Record High, SPR Draw Slows, Cushing Remain...
ZeroHedge
2 months ago
Great Rewiring: US Supports Iraq-Syria Oil Pipeline To Erode Tehran's Hormuz Lev...
ZeroHedge
2 months ago
Traders call Trump's Hormuz bluff at their peril
The Economic Times (India)
2 months ago
Comfortably Bomb
ZeroHedge
2 months ago
Dubai's New East Coast Port Signals The Beginning Of End For Iran's Hormuz Lever...
ZeroHedge
2 months ago
Dispute Whether Hormuz Is Open Intensifies As Ships Continue Transiting
ZeroHedge
2 months ago
Oil prices spike as Hormuz traffic slows to multi-week low
Middle East Eye
2 months ago
Oil Jumps, Futures Drop On Fresh Iran Strikes, Hormuz Confusion
ZeroHedge
2 months ago
IEA Warns Escalation In US-Iran Hostilities Could Upend Oil Surplus Forecast
ZeroHedge
2 months ago
Iran fast-tracks 11 million barrels of oil as Trump threatens blockade
Middle East Eye
2 months ago
63 Million Barrels Of Iranian Oil Stuck At Sea After US Pulls Iran Sanction Waiv...
ZeroHedge
2 months ago
"They're Scum": Trump Says US-Iran Ceasefire Is Over, Sending Oil Higher
ZeroHedge
2 months ago
US cancels waiver allowing Iran oil sales as Gulf vessels attacked
Middle East Eye
2 months ago
Citi Expects Oil To Sink To $60 As Hormuz Traffic Normalizes
ZeroHedge
2 months ago
Red Sea Blockage Fears: Cargo Ship Attacked Off Southwest Yemen
ZeroHedge
2 months ago
Europe Capitulates, Sees Iranian Hormuz Fee Collection As 'Inevitable'
ZeroHedge
2 months ago
WTI Holds Losses As SPR Drain Slows, Cushing Just Off 'Tank Bottoms'
ZeroHedge
2 months ago
Hormuz Tanker Traffic Plunges After Fresh US-Iran Strikes
ZeroHedge
2 months ago
Oil Markets Are Pricing A Supply Surge That Isn't Guaranteed
ZeroHedge
2 months ago
Tanker Rates Nearly Halve As Hormuz Shipping Normalizes
ZeroHedge
3 months ago
Tanker Owners Having The Best Week Of The Hormuz Crisis As VLCC Rates Soar
ZeroHedge
3 months ago
"We Must Act": TotalEnergies CEO Joins Calls To Rewire Gulf Energy Flows Around...
ZeroHedge
3 months ago
"This May Be Iran's First Misstep - And Proof Leverage Isn't Total"
ZeroHedge
3 months ago
Iran Oil Exports Through Hormuz Hit Wartime High
ZeroHedge
3 months ago
When Will Gasoline Prices Return To Pre-War Levels?
ZeroHedge
3 months ago
Energy Cliff, Supply Chain Shock: The Toxic Cocktail Behind The Urgent Push For...
ZeroHedge
3 months ago
Hormuz Normalization Begins As Saudi Supertankers Exit And A Flood Of Persian Gu...
ZeroHedge
3 months ago
"Zero Hormuz Dependency": UAE Races To Rewire Energy Flows, Bypassing Chokepoint...
ZeroHedge
3 months ago
Big Oil Tankers Abruptly U-Turn Toward Hormuz Ahead Of US-Iran Peace Deal Signin...
ZeroHedge
3 months ago
Iranian Tankers Cross US Naval Blockade After Trump Deal Allows Iran To Restart...
ZeroHedge
3 months ago
U.S.-Iran Deal Doesn't Mean A Swift Return Of Oil And Gas Flows
ZeroHedge
3 months ago
Oil supplies could still take months to get back on track despite a U.S.-Iran ce...
Fast Company
3 months ago
Strait Of Hormuz Reopens, But Global Oil Supply Recovery Could Take Months
Free Press Journal